When the Numbers Say Fine but the Fear Says Otherwise: Understanding Financial Anxiety
The account is fine and the fear is not. Why money anxiety stops tracking the numbers.
In this article
The account balance that never feels like enough
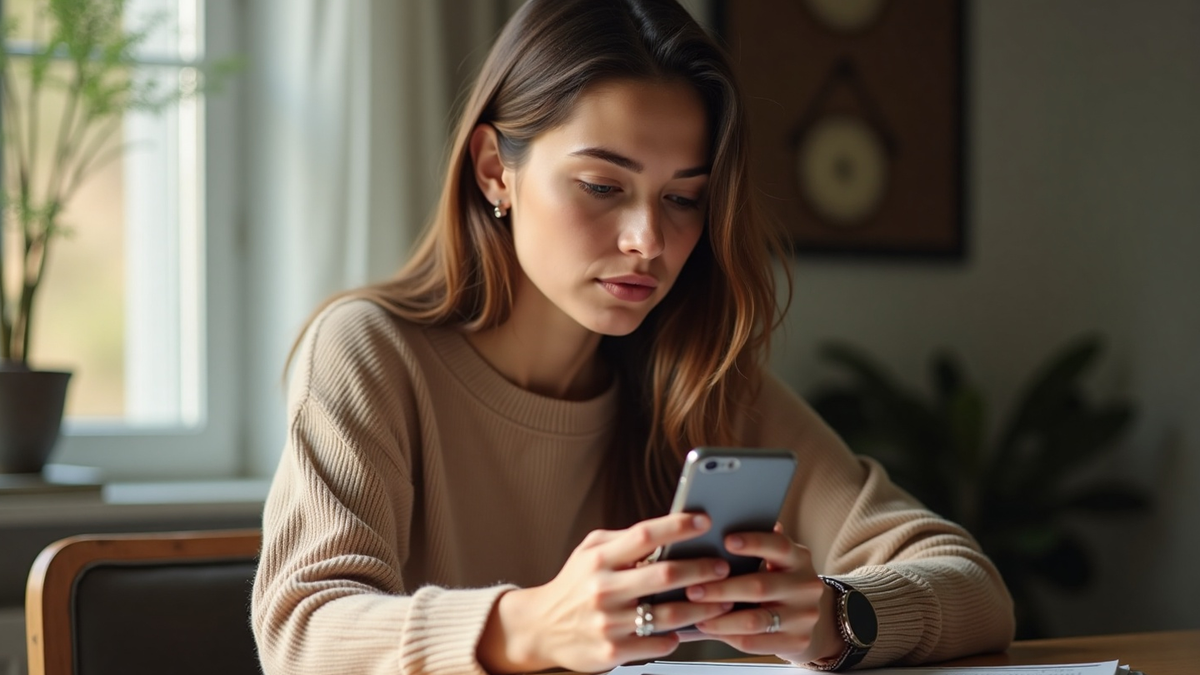
I want to start with a client I will call Marta. She had a stable job, a reasonable emergency fund, and no debt. She also checked her bank account eleven times on the day she told me about it. Not because anything had changed. Not because a payment was due. She checked because not checking felt unbearable.
Marta is not unusual. In my clinical practice I work with many people whose relationship with money is governed far more by fear than by facts. They have savings, yet they feel broke. They have paid their bills, yet they lie awake adding figures in their heads. The anxiety is real — but it is not a response to a real financial crisis. It is a nervous system that learned, somewhere earlier in life, that scarcity was the default state, and has not yet received the memo that the circumstances changed.
This distinction matters enormously, because financial anxiety and a genuine budget problem are not the same thing, and they do not respond to the same solutions.
Why the fear outlives the facts
Neuroscience and attachment research both point to the same mechanism: the brain encodes threat patterns early, and those patterns become templates for reading the world. If you grew up in a household where money was chronically tight — where you heard your parents argue about bills, where treats were rare and unexpected expenses caused visible panic — your nervous system catalogued all of that. It learned: *money is dangerous, scarcity is always around the corner, vigilance is survival.*
That learning is not irrational given its original context. It was adaptive. The problem is that the brain does not automatically update the template when your circumstances improve. The child who watched a parent cry over an overdue notice becomes the adult who feels a surge of cortisol when a bill arrives, even when their account can cover it three times over.
Psychologists sometimes call this a mismatch: the emotional response is calibrated to an old reality, not the current one. The compulsive account-checking, the inability to spend even on necessities without guilt, the catastrophic "what if we lose everything" spiral — these are not character flaws or irrationality. They are old protective patterns running on outdated information.
Money worry versus money anxiety
There is a difference between functional concern about finances and anxiety that has detached from the actual numbers. Worry, in its healthy form, prompts action: you notice a problem, you make a plan, you feel some relief. Anxiety is stickier. It circles. It does not resolve when you look at the account, because the temporary reassurance only feeds the cycle.
| Sign | Money worry | Money anxiety |
|---|---|---|
| Trigger | A real gap between income and expenses | A balance that is objectively fine |
| After checking the account | Temporary relief, then moves on | Brief relief, then urge to check again |
| Response to a plan | Calms down once a plan is in place | Planning brings little lasting comfort |
| Physical symptoms | Mild, situational | Chronic tension, sleep disruption, nausea |
| Relationship to facts | Shifts when the facts shift | Persists even when facts improve |
If you recognise yourself in the right-hand column more often than the left, the primary work is not budgeting. It is nervous system regulation.
The budget costume problem
Here is where I want to be honest with you about something I see often in clinical work: many people with financial anxiety seek out budgeting apps, spreadsheets, and financial advice, and these tools do not help — or sometimes make things worse. That is because they are applying a planning solution to an anxiety problem.
A budget solves a knowledge gap. Anxiety is not a knowledge gap. If you are anxious, you probably already know your numbers. You may know them obsessively. The problem is that knowledge is not reaching the part of your brain that is generating the fear.
This does not mean that budgeting is useless. For someone with a real shortfall, a clear plan is essential. But if the fear persists after the plan is in place, if no amount of information quietens the alarm, that is a signal that something else is happening — something that deserves a different kind of attention.
Practical steps that actually address the right problem
Create a defined checking ritual
Compulsive account-checking provides micro-doses of reassurance that maintain the anxiety cycle rather than resolving it. The alternative is not to stop checking — it is to check deliberately and at a set time. Choose one or two fixed moments per day (or per week, depending on your situation) when you look at your finances. Outside those times, you do not check. When the urge arises between rituals, you name it: *that is anxiety, not information.* This shifts checking from an anxiety-driven compulsion to a purposeful behaviour.
Name the specific feared scenario
Vague dread is more powerful than a named fear. I often ask clients: "If the worst happened, what exactly would that look like?" Not to catastrophise, but to bring the feared scenario out of the fog. Is it losing your job? A sudden large expense? Ending up unable to pay rent? Write it down specifically. Once it has a shape, you can assess it more clearly — and you can distinguish between *this could actually happen and I should prepare* versus *this is extremely unlikely and I am treating it as certain.*
Separate planning from worrying
Planning has a beginning, a middle, and an end. You identify a question, you gather information, you reach a decision or take an action. Worry loops. It revisits the same territory without resolution.
A useful practice: set a 20-minute planning window and use it to address one concrete financial question. Write down what you decided or what action you will take. Then close the topic. If the thoughts return outside that window, that is worry, not planning — and it does not need to be answered again right now.
Common behaviours and what to try instead
| Behaviour | What it signals | A different approach |
|---|---|---|
| Checking the account more than three times daily | Anxiety cycle, not information need | Fixed checking times once or twice a day |
| Avoiding looking at finances entirely | Avoidance anxiety | Brief scheduled review with a trusted person if needed |
| Recalculating figures already known | Reassurance-seeking | Write down the answer once, refer back to that note |
| Refusing to spend when there is enough | Scarcity template running | Small intentional spend with written reflection after |
| Arguing about money disproportionately | Anxiety displaced onto others | Name the fear privately before the conversation |
When to seek support
Nothing I have described here is a diagnosis. Financial anxiety exists on a spectrum, and for many people the practical steps above will bring meaningful relief over time. But if the anxiety is significantly disrupting your sleep, your relationships, or your ability to work — or if it is accompanied by persistent low mood, panic attacks, or intrusive thoughts — then working with a mental health professional is not an indulgence. It is appropriate care for a real problem.
At Dzeny, we work with the emotional and psychological dimensions of money stress, not because we are financial advisors, but because we understand that for many people the problem was never really about the numbers.
References
- 1.Kahneman, D.. Thinking, Fast and Slow, 2011. Farrar, Straus and Giroux (2011)
- 2.Baddeley, A.. Working Memory, Thought, and Action, 2007. Oxford University Press (2007)
- 3.Salkovskis, P.M.. The importance of behaviour in the maintenance of anxiety and panic: a cognitive account. Behavioural Psychotherapy, 1991 (1991)
- 4.Abramowitz, J.S., Tolin, D.F., Street, G.P.. Paradoxical effects of thought suppression: a meta-analysis of controlled studies. Clinical Psychology Review, 2001 (2001)
- 5.LeDoux, J.. The Emotional Brain: The Mysterious Underpinnings of Emotional Life, 1996. Simon and Schuster (1996)
- 6.Bradley, G.L., Gillies, E.A.. Financial stress, anxiety, and well-being: evidence from a national survey. Journal of Financial Therapy, 2019 (2019)
Frequently Asked Questions
Written by
Valentina Lipskaya
Clinical Psychologist · Gestalt Therapist · CBT Specialist · ICF Certified Coach · MBA Professor
Panic Disorder, Anxiety, CBT & Gestalt Therapy
Valentina Lipskaya is a certified clinical psychologist and gestalt therapist specializing in panic disorders, anxiety, and neurological conditions. With over 15 years in psychology and 7 years of hands-on clinical practice, she has helped more than 750+ clients overcome panic, chronic anxiety, and psychosomatic conditions — without medication. Her work at Dzeny translates evidence-based therapeutic methods into practical, accessible guidance for everyday mental health.